Retirement Planning for Self-Employed Individuals in Rural Areas: Overcoming Challenges for a Secure Future
Retirement Planning for Self-Employed Individuals in Rural Areas
Retirement planning is important for everyone, but it can be particularly challenging for self-employed individuals living in rural areas. Without the benefits of a traditional employer-sponsored retirement plan, it’s crucial to take proactive steps to secure your financial future.
1. Start Early: Time is your biggest ally when it comes to retirement savings. The earlier you start saving, the more time your money has to grow. Even if you’re just starting out as a self-employed individual in a rural area, make retirement planning a priority from day one.
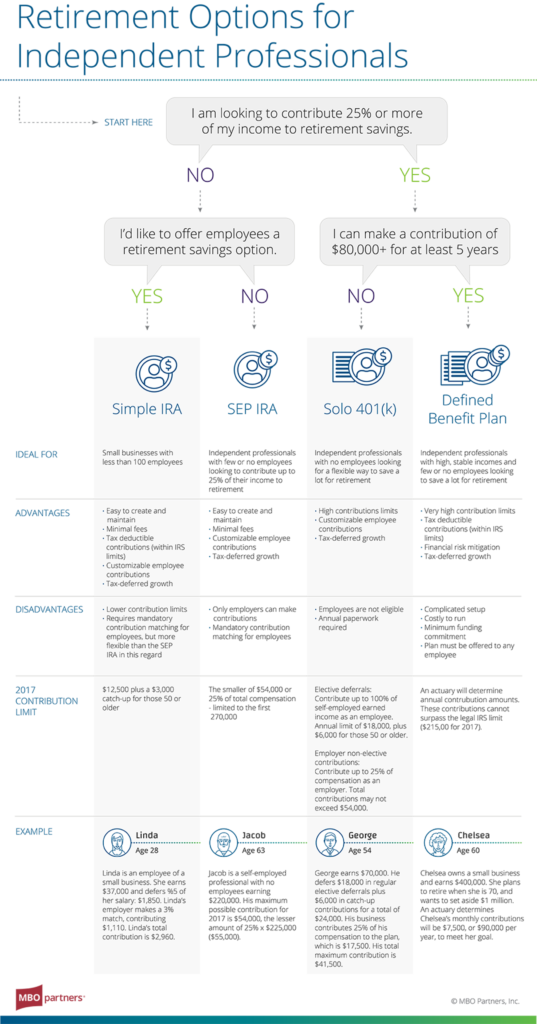
2. Set Up an Individual Retirement Account (IRA): IRAs are excellent tools for self-employed individuals because they offer tax advantages and flexibility. You can choose between a Traditional IRA or a Roth IRA, depending on your personal circumstances and goals. Consult with a financial advisor or tax professional to determine which type of IRA suits you best.
3. Consider Simplified Employee Pension (SEP) IRA: If you have employees or plan on hiring them in the future, consider setting up SEP IRA accounts for both yourself and your employees. A SEP IRA allows contributions based on a percentage of compensation and offers potential tax deductions.
4. Maximize Contributions: Contribute as much as you can afford to your retirement accounts each year, taking advantage of any available catch-up contributions if you’re over 50 years old.
5. Diversify Your Investments: Don’t put all of your eggs in one basket by investing solely in one asset class or industry sector. Diversification helps spread risk and increase potential returns over time.
6. Create Multiple Streams of Income: In rural areas where self-employment opportunities may be limited, diversifying income sources can help ensure financial stability during retirement years. Explore side gigs or part-time jobs that align with your skills and interests while generating additional income streams.
7. Seek Professional Advice: Working with a certified financial planner or retirement planning specialist can provide expert guidance tailored to your specific circumstances. They can help you develop a personalized retirement plan and adjust it as needed over time.
8. Consider Long-Term Care Insurance: As rural areas may have limited access to healthcare services, it’s essential to plan for potential long-term care needs in retirement. Long-term care insurance can help cover the costs of assisted living facilities or nursing homes should the need arise.
9. Monitor and Adjust Your Plan: Regularly review your retirement plan and make adjustments based on changes in income, expenses, or goals. Life circumstances may change, so it’s crucial to stay proactive about ensuring your retirement savings stay on track.
10. Stay Informed about Retirement Options: Keep yourself updated on any changes in tax laws, investment opportunities, or retirement plans that may benefit self-employed individuals specifically.
In conclusion, self-employed individuals in rural areas face unique challenges when it comes to retirement planning but with careful consideration and proactive steps taken early on, a secure financial future is attainable. Start saving early, diversify investments, seek professional advice when needed, and continuously monitor and adjust your plan to ensure you’re on track for a comfortable retirement life.